Futures Risk Reward Calculator 2026: Free R:R & Breakeven Tool
Use this futures risk reward calculator to measure the relationship between your planned stop and target before a futures trade. Select a contract, enter your direction, entry, stop, target and contract quantity, and the tool calculates dollar risk, dollar reward, reward-to-risk ratio, breakeven win rate, and estimated results after fees and slippage.
A futures risk reward calculator is different from a position-size or profit calculator. Position sizing asks how many contracts fit inside a defined risk budget. A profit calculator evaluates a specific price move. Risk/reward analysis asks whether the potential target is large enough relative to the planned loss if the stop is reached.
Quick Answer
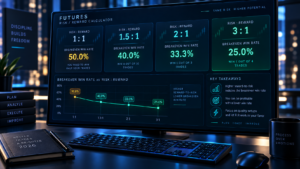
A futures risk reward calculator compares the dollar amount you could lose at the stop with the dollar amount you could gain at the target. If a setup risks $200 to pursue $400, the reward-to-risk ratio is 2:1, often written as 2R of potential reward for 1R of risk. Ignoring trading costs, a 2:1 setup has a mathematical breakeven win rate of about 33.33%. A favorable ratio does not make the trade profitable by itself because actual results depend on win rate, execution, costs and whether the strategy’s assumptions hold.
Affiliate Disclosure: TradeboticsAI may receive compensation when readers complete qualifying actions through certain links. NinjaTrader buttons on this page are affiliate links. The calculator and educational conclusions do not change based on compensation.
Futures Risk Reward Calculator
This interactive futures risk reward calculator converts entry, stop and target prices into ticks and dollars. It handles both long and short trades and lets you include estimated round-turn fees and slippage. The output shows gross risk, gross reward, estimated net reward, reward-to-risk ratio and breakeven win rate.
Calculate Futures Risk and Reward
—
—
—
—
—
—
—
—
—
Educational estimate only. A stop does not guarantee execution at the entered price. Fees, slippage, partial fills and market gaps can change realized results. A higher R:R ratio does not imply a higher probability of success.
How a Futures Risk Reward Calculator Works
A futures risk reward calculator begins with three price levels: entry, protective stop and target. The distance from entry to stop defines the planned adverse move. The distance from entry to target defines the planned favorable move. Because futures contracts have contract-specific tick values, both distances are converted to ticks before being converted to dollars.
For a long trade, risk is measured below the entry and reward is measured above it. For a short trade, the directions reverse. The ratio itself is unitless: risking $100 to target $200 and risking $500 to target $1,000 both produce the same 2:1 reward-to-risk ratio.
The dollar values still matter because a strategy can have an attractive ratio while exposing too much of the account on each trade. Risk/reward analysis and position sizing should therefore be used together rather than as substitutes.
Futures Risk Reward Calculator Formula
The core futures risk reward calculator formula is straightforward.
Risk distance = absolute difference between entry and stop
Reward distance = absolute difference between target and entry
Risk ticks = risk distance ÷ tick size
Reward ticks = reward distance ÷ tick size
Dollar risk = risk ticks × tick value × contracts
Dollar reward = reward ticks × tick value × contracts
Reward-to-risk ratio = dollar reward ÷ dollar risk
When the same contract quantity applies to both the stop and target, quantity cancels out of the ratio. Two ES contracts and one ES contract can have the same R:R if entry, stop and target are identical. Contract quantity changes the dollars at risk, not the geometric ratio between the stop and target.
Costs complicate the picture. Fees and slippage reduce the amount retained when a target is reached and increase the realized loss if a stop is hit. That is why the calculator reports both gross values and estimated cost-adjusted values.
Breakeven Win Rate From a Futures Risk Reward Calculator
One of the most useful outputs from a futures risk reward calculator is the theoretical breakeven win rate. If the average winning trade produces R units of reward for every 1 unit of risk, the no-cost breakeven win rate is:
Breakeven win rate = 1 ÷ (1 + R)
| Reward : Risk | Theoretical Breakeven Win Rate | Meaning Before Costs |
|---|---|---|
| 0.5 : 1 | 66.67% | Wins must occur frequently because average reward is smaller than average risk. |
| 1 : 1 | 50.00% | Average win and average loss are equal. |
| 1.5 : 1 | 40.00% | Each average win is 1.5 times the planned risk. |
| 2 : 1 | 33.33% | One full target offsets two full 1R losses before costs. |
| 3 : 1 | 25.00% | A lower win rate can break even if full 3R targets are actually realized. |
| 4 : 1 | 20.00% | The mathematical threshold falls further, but reaching large targets may be less frequent. |
This table is arithmetic, not a strategy recommendation. Real trading rarely consists of perfectly repeated full-stop losses and full-target wins. Partial exits, breakeven stops, slippage, commissions and discretionary management change the realized distribution.
A trader should therefore compare theoretical breakeven with the strategy’s actual historical and live win rate after costs. A 3:1 target is not automatically superior to a 1.5:1 target if the larger target is reached far less often.
Contract Tick Values Used by the Futures Risk Reward Calculator
The futures risk reward calculator includes common U.S. futures presets because the same number of ticks can represent very different dollars across contracts. CME Group currently lists Micro E-mini S&P 500 futures at a 0.25-point minimum tick worth $1.25 and Micro E-mini Nasdaq-100 futures at a 0.25-point minimum tick worth $0.50.
| Symbol | Contract | Tick Size | Tick Value | Point Value |
|---|---|---|---|---|
| ES | E-mini S&P 500 | 0.25 | $12.50 | $50 |
| MES | Micro E-mini S&P 500 | 0.25 | $1.25 | $5 |
| NQ | E-mini Nasdaq-100 | 0.25 | $5.00 | $20 |
| MNQ | Micro E-mini Nasdaq-100 | 0.25 | $0.50 | $2 |
| YM | E-mini Dow | 1.00 | $5.00 | $5 |
| MYM | Micro E-mini Dow | 1.00 | $0.50 | $0.50 |
| RTY | E-mini Russell 2000 | 0.10 | $5.00 | $50 |
| M2K | Micro E-mini Russell 2000 | 0.10 | $0.50 | $5 |
| CL | WTI Crude Oil | 0.01 | $10.00 | $1,000 |
| MCL | Micro WTI Crude Oil | 0.01 | $1.00 | $100 |
| GC | Gold | 0.10 | $10.00 | $100 |
| MGC | Micro Gold | 0.10 | $1.00 | $10 |
Contract specifications should be verified before live use. The exchange, not TradeboticsAI, is the authoritative source for the contract’s current minimum tick and multiplier.
See the
official CME Group Micro E-mini contract specifications
for current tick information.
Futures Risk Reward Calculator Examples
Example 1: ES With a 2:1 Target
Assume ES is entered long at 6,000, the stop is 5 points lower at 5,995 and the target is 10 points higher at 6,010. ES is worth $50 per point, so one contract risks $250 and targets $500. The futures risk reward calculator reports a 2:1 ratio and a no-cost breakeven win rate of 33.33%.
Example 2: MNQ With a 1.5:1 Target
Suppose MNQ is entered long at 21,000 with a 20-point stop and a 30-point target. MNQ is worth $2 per point. One contract therefore risks $40 and targets $60. Four contracts risk $160 and target $240 before costs, while the ratio remains 1.5:1.
Example 3: Short CL Trade
Assume CL is sold at $70.00, with a stop at $70.20 and target at $69.60. The stop is $0.20 away and the target is $0.40 away. Since CL is worth $1,000 per full dollar of price movement, gross risk is $200 per contract and gross reward is $400. The short direction changes which side of entry is favorable, but the ratio is still 2:1.
Example 4: Same Setup, Different Contract Size
A five-point stop and ten-point target produce the same 2:1 ratio in ES and MES, but the dollars differ by a factor of ten. One ES risks $250 and targets $500, while one MES risks $25 and targets $50. This is why risk/reward and position sizing must be evaluated separately.
Fees and Slippage in a Futures Risk Reward Calculator
A headline ratio can overstate the economics of a small-target strategy when costs are meaningful relative to the target. If gross reward is $100 and gross risk is $50, the ratio appears to be 2:1. If the full round-trip cost estimate is $10, the cost-adjusted result is closer to $90 of net reward versus $60 of loss including costs.
The futures risk reward calculator therefore displays estimated costs separately. The fee field is entered as a round-turn amount per contract. The slippage input is entered as an estimated total number of ticks per contract and converted to dollars using the selected contract’s tick value.
Do not double-count slippage. If you are analyzing a completed trade with actual entry and exit fills, execution slippage may already be embedded in those prices. Cost inputs are most useful for planning hypothetical scenarios or for adding costs that are not already represented by the entered fills.
Execution costs can also vary by broker, exchange fees, routing arrangement, contract and trading volume. The calculator intentionally does not hard-code one universal commission.
Futures Risk Reward Calculator vs Position Size Calculator
The futures risk reward calculator measures the quality of the planned payoff geometry. The position-size calculator measures how many contracts fit inside a defined dollar-risk budget.
Use both in sequence. First define the strategy-based entry, invalidation level and target. Measure the resulting R:R. Then decide how much account capital you are willing to risk and calculate how many whole contracts fit inside that budget.
Use our
Futures Position Size Calculator 2026
for the second step.
If you want to calculate the dollar result of an actual entry-to-exit move instead, use the
Futures Profit Calculator 2026
.
Risk/Reward Ratio vs Trading Expectancy
A futures risk reward calculator provides one side of a strategy’s economics. The other major input is how often the strategy wins and how much of the planned reward and risk are actually realized on average.
A simplified expectancy formula expressed in R units is:
Expectancy = (win rate × average win in R) − (loss rate × average loss in R)
Suppose a strategy wins 40% of trades, the average winner is 2R and the average loser is 1R. Before costs, expectancy is 0.40 × 2 − 0.60 × 1 = +0.20R per trade. If the same strategy wins only 30%, expectancy becomes 0.30 × 2 − 0.70 × 1 = -0.10R.
This demonstrates why chasing a high reward-to-risk ratio without measuring actual win rate is incomplete. A 4R target may look attractive on a chart but have poor expectancy if it is rarely reached or if winning trades are routinely exited early.
Trading journals are useful for comparing planned R:R with realized R multiples. See our
Best Futures Trading Journals 2026
comparison for tools that track expectancy, drawdown and setup performance.
Using a Futures Risk Reward Calculator With Prop-Firm Accounts
Prop-firm traders can use the futures risk reward calculator for trade-level planning, but the ratio does not know how close the account is to a daily loss or maximum drawdown boundary.
A trade that looks acceptable at 2:1 may still be too large for an account with only a small remaining buffer. Use the account-level drawdown calculation first, define a smaller per-trade budget, size the position, and only then evaluate whether the target-to-stop structure fits the strategy.
Our
Prop Firm Drawdown Calculator 2026
estimates static, trailing and end-of-day drawdown floors from user-entered rules. Multi-account traders should repeat that process for each account because follower accounts can have different remaining buffers.
For account-replication workflows, see our
Best Futures Trade Copiers 2026
guide.
Common Futures Risk/Reward Mistakes
Choosing the Target Only to Force a Better Ratio
A target should come from the strategy or market structure, not from a desire to make the calculator display 3:1. Moving a target farther away improves the mathematical ratio while potentially reducing the probability that price reaches it.
Moving the Stop Artificially Close
The same problem works in reverse. Tightening the stop can make the displayed R:R look better but may place the stop inside normal market noise. The futures risk reward calculator measures the distances you enter; it cannot decide whether those levels are technically valid.
Ignoring Costs
Fees and slippage have a larger proportional impact on small targets and high-turnover strategies. Compare gross and estimated net outcomes.
Assuming R:R Predicts Win Probability
A 3:1 setup does not imply a 75% chance of winning or any other probability. The ratio describes payoff size, not forecast accuracy.
Ignoring Partial Exits
Scaling out at 1R and leaving only part of the position for 3R produces a different average realized reward than a full-position 3R target.
Using the Same Dollar Risk Across Accounts Without Checking Limits
Prop-firm drawdown, account size and personal risk tolerance can differ. Position size should reflect the specific account rather than copying a leader quantity blindly.
Futures Risk Reward Calculator FAQ
What is a futures risk reward calculator?
A futures risk reward calculator compares the planned dollar loss from entry to stop with the planned dollar gain from entry to target. It can also calculate the reward-to-risk ratio and theoretical breakeven win rate.
What does a 2:1 risk reward ratio mean?
It means the planned reward is twice the planned risk. If the stop represents $200, a 2:1 target represents $400 before fees and slippage.
What win rate is needed for a 2:1 setup?
Ignoring costs and assuming full 2R wins and full 1R losses, the theoretical breakeven win rate is 33.33%. Real strategies can require a higher win rate because of costs and imperfect exits.
Is 3:1 always better than 2:1?
No. A larger target improves the payoff ratio but may be reached less often. Strategy expectancy depends on both realized payoff and realized win rate.
Does contract quantity change the R:R ratio?
Not when the same quantity applies to both stop and target. Quantity scales the dollar risk and reward together, so the ratio remains the same.
Can I use the calculator for short trades?
Yes. Select Short, place the stop above entry and target below entry, and the futures risk reward calculator handles the direction automatically.
Does this calculator include trading fees?
Yes. You can enter an estimated round-turn fee per contract plus estimated slippage in ticks. The tool displays those costs separately and shows cost-adjusted target and stop outcomes.
Does a good risk reward ratio guarantee profitability?
No. A good-looking ratio cannot guarantee that the target is realistic or that a strategy has positive expectancy. Win rate, execution, costs, market regime and discipline all matter.
Should I calculate risk reward before position size?
Usually the trading plan should define entry, stop and target first. Then evaluate the R:R and size the number of contracts from a separate account-risk budget.
Can I use this with a prop-firm evaluation?
Yes for trade-level math, but you must separately respect the firm’s current daily-loss, drawdown, consistency and position-limit rules.
Final Verdict: Futures Risk Reward Calculator for 2026
A useful futures risk reward calculator should make the trade’s planned payoff transparent before the order is placed. Entry, stop and target determine the geometric ratio; contract tick value and quantity convert that geometry into actual dollars.
The most important lesson is that R:R is not a standalone quality score. A 2:1 setup requires a lower theoretical breakeven win rate than a 1:1 setup, but that advantage only matters if the strategy can realize those winners often enough after fees, slippage and trade management.
Use the tool as part of a sequence: define valid trade levels, calculate reward versus risk, set a separate dollar-risk budget, size the position, check prop-account constraints when relevant, and review realized R multiples in a trading journal.
The futures risk reward calculator does not predict market direction, guarantee a target fill or determine whether any specific trade should be taken.