Futures Position Size Calculator 2026: Free Risk Per Trade Tool
Use this futures position size calculator to estimate how many futures contracts fit inside a defined dollar-risk budget before you place a trade. Select a common contract such as ES, MES, NQ, MNQ, CL or GC, enter your account size, risk percentage and stop distance, and the tool calculates your maximum whole-contract position based on tick size and tick value.
The futures position size calculator is designed for educational risk planning. It does not tell you where a stop should be placed, whether a trade is suitable, or whether you should take a position. It also separates risk-based sizing from broker margin, because having enough margin to open a contract does not mean the position fits your risk plan.
Quick Answer
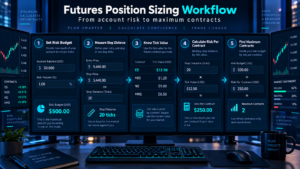
A futures position size calculator works from four core inputs: the amount you are willing to risk, the stop distance, the contract’s minimum tick size and the dollar value of each tick. The basic method is: risk per contract = stop ticks × tick value, then maximum contracts = floor(risk budget ÷ risk per contract). This page also lets you include estimated slippage and round-turn fees so the calculation is more conservative than stop distance alone.
Affiliate Disclosure: TradeboticsAI may receive compensation when readers complete qualifying actions through certain links. The NinjaTrader buttons on this page are affiliate links. The calculator and educational explanations are editorial and do not change based on compensation.
Futures Position Size Calculator
This interactive futures position size calculator sizes a position from your maximum planned loss. Choose a preset contract or select Custom if you need a different tick size and tick value. The result is always rounded down to a whole number of contracts.
Calculate Your Maximum Contract Size
Educational estimate only. Stops can fill worse than expected, fees vary, contract specifications can change, and broker/prop-firm margin or position limits are separate constraints. Verify the exact contract specification and your account rules before trading.
How the Futures Position Size Calculator Works
The futures position size calculator starts with a risk budget rather than with buying power. If a $50,000 account uses a hypothetical 1% risk budget, that budget is $500. The next step is determining how many ticks separate the intended entry from the protective stop. The calculator then multiplies that distance by the contract’s tick value.
CME Group teaches the same core logic in its position-sizing education: traders need to know where the stop is located and how much of the account they are willing to risk. CME’s example shows that a 50-tick stop with a $10 tick value produces $500 of risk for one contract.
Read the
CME Group position-size lesson
for the exchange’s educational explanation.
Our calculator goes one step further by letting you add estimated slippage and round-turn fees. Those inputs do not predict your actual fill, but they prevent the calculator from pretending that the stop-distance calculation is the only possible trading cost.
Futures Position Size Calculator Formula
The core futures position size calculator formula is intentionally simple:
Risk budget = account balance × risk percentage
Stop ticks = absolute entry-to-stop distance ÷ tick size
Risk per contract = stop ticks × tick value
Maximum contracts = floor(risk budget ÷ risk per contract)
If you add slippage and fees, the adjusted risk per contract becomes:
Adjusted risk per contract = (stop ticks + estimated slippage ticks) × tick value + estimated round-turn fees
The use of floor matters. If the math says 2.8 contracts, the result is two contracts, not three. Futures contracts are discrete units, and rounding up would intentionally exceed the input risk budget.
If the result of the calculator is zero, one contract already exceeds the risk budget at the selected stop distance. That is information, not an error. A smaller contract such as MES instead of ES or MNQ instead of NQ may provide finer sizing, but only if it fits your strategy and account rules.
Common Contract Inputs for a Futures Position Size Calculator
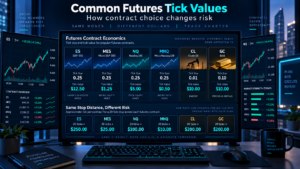
Tick size and tick value are not interchangeable. Tick size is the minimum price movement; tick value is what that movement is worth for one contract. CME Group notes, for example, that ES moves in 0.25-point ticks worth $12.50, while MES uses the same 0.25-point increment but a $1.25 tick value. Micro contracts can therefore offer more granular position sizing.
| Symbol | Contract | Tick Size | Tick Value | Approx. Value per Point |
|---|---|---|---|---|
| ES | E-mini S&P 500 | 0.25 | $12.50 | $50 |
| MES | Micro E-mini S&P 500 | 0.25 | $1.25 | $5 |
| NQ | E-mini Nasdaq-100 | 0.25 | $5.00 | $20 |
| MNQ | Micro E-mini Nasdaq-100 | 0.25 | $0.50 | $2 |
| YM | E-mini Dow | 1.00 | $5.00 | $5 |
| MYM | Micro E-mini Dow | 1.00 | $0.50 | $0.50 |
| RTY | E-mini Russell 2000 | 0.10 | $5.00 | $50 |
| M2K | Micro E-mini Russell 2000 | 0.10 | $0.50 | $5 |
| CL | WTI Crude Oil | 0.01 | $10.00 | $1,000 |
| MCL | Micro WTI Crude Oil | 0.01 | $1.00 | $100 |
| GC | Gold | 0.10 | $10.00 | $100 |
| MGC | Micro Gold | 0.10 | $1.00 | $10 |
Contract specifications can change or new products can be introduced, so verify the current exchange specification before relying on a preset. CME currently confirms MES at $1.25 per 0.25-point tick and MNQ at $0.50 per 0.25-point tick. CME’s futures education also explains that one CL tick is $10.
Futures Position Size Calculator Examples
Example 1: ES With a 20-Tick Stop
Assume a $50,000 risk reference, a 1% budget and a 20-tick ES stop. The budget is $500. ES is worth $12.50 per tick, so one contract has $250 of stop-distance risk. Ignoring additional costs, the futures position size calculator returns two ES contracts because $500 ÷ $250 = 2.
Example 2: MES With the Same 20-Tick Stop
With MES, a 20-tick stop represents $25 per contract because each tick is $1.25. Using the same hypothetical $500 budget, the arithmetic allows 20 MES contracts before fees and slippage. That does not mean 20 contracts are appropriate; it only demonstrates how micro contracts create smaller sizing increments.
Example 3: MNQ With a 40-Tick Stop
MNQ has a $0.50 tick value. Forty ticks therefore represent $20 per contract before costs. A $200 fixed risk budget would mathematically allow 10 MNQ contracts. The calculator will reduce that number if you add slippage or round-turn fees.
Example 4: CL With a 25-Tick Stop
CME explains that a WTI crude oil futures tick is worth $10. A 25-tick stop therefore represents $250 of price risk for one CL contract. If your selected budget is below $250, the calculator correctly returns zero CL contracts before considering additional costs.
Futures Position Size vs Futures Margin
Margin and risk are different measurements. Broker day-trading margin determines how much collateral may be required to open or maintain a position under that broker’s rules. The futures position size calculator instead asks how much the position could lose between the intended entry and stop, based on tick value.
You can therefore have enough margin to open five contracts while your risk calculation says one contract—or zero contracts—fits the planned loss budget. Margin availability should never be treated as a position-sizing recommendation.
Broker margin can also change during volatility, around market events or for overnight positions. A stop order is not a guarantee of execution at the stop price. Gaps, fast markets and liquidity conditions can produce a worse fill.
If you are still choosing an execution environment, see our
Best Automated Futures Trading Software 2026
comparison. Traders running always-on systems can also review our
Best Futures Trading VPS 2026
guide.
Using a Futures Position Size Calculator for Prop-Firm Accounts
A prop-firm trader can use the futures position size calculator with a fixed dollar risk budget instead of an account-balance percentage. This can be useful because an advertised evaluation account size is not necessarily the amount you can actually lose before violating the firm’s drawdown rules.
For example, if the relevant constraint is a daily loss limit, trailing drawdown or personal session cap, you can enter a smaller fixed budget that reflects the amount of risk you want one trade to consume. The calculator does not know the firm’s rules, so it will not automatically enforce daily loss limits, consistency rules, scaling rules or maximum contract counts.
This distinction is especially important when copying a trade across multiple accounts. Position size may need to be calculated separately for each follower account rather than assuming one leader quantity fits every account.
For multi-account infrastructure, see our
Best Futures Trade Copiers 2026
comparison.
Risk Controls Beyond the Futures Position Size Calculator
The futures position size calculator solves only one problem: translating a planned risk budget and stop distance into a maximum whole-contract quantity. It does not replace account-level safeguards.
- Daily loss limit: stop additional trading after a defined session loss.
- Maximum position limit: prevent accidental oversizing.
- Order confirmation: reduce quantity-entry mistakes.
- Bracket orders: attach predefined stop and target logic where appropriate.
- Connection monitoring: detect platform, data or broker disconnects.
- Emergency flatten procedure: define what to do when positions or accounts become unsynchronized.
- Trade journal: review whether actual position size matched the planned position size.
A journal can expose risk drift over time. Our
Best Futures Trading Journals 2026
comparison covers tools for drawdown, expectancy, MAE/MFE and multi-account review.
Common Futures Position Sizing Mistakes
Using Points Instead of Ticks
Each contract has its own tick size and tick value. Always convert the entry-to-stop distance into ticks correctly before applying this position-sizing formula.
Rounding Up
If the calculated result is 1.9 contracts, the maximum whole-contract answer inside the budget is one. Rounding up breaks the risk constraint.
Ignoring Fees and Slippage
The stop-distance calculation is not the same as guaranteed realized loss. Our tool includes optional fields for estimated fees and slippage precisely because live results can differ from the theoretical stop.
Confusing Nominal Account Size With Loss Capacity
This is especially relevant for evaluation and prop-firm accounts. The meaningful risk reference may be a drawdown cushion or a personal daily limit rather than the account label shown in marketing.
Using the Same Size for Every Contract
One ES, one MNQ and one CL contract have very different tick economics. A proper sizing tool should recalculate quantity every time the contract or stop distance changes.
Futures Position Size Calculator FAQ
How do I calculate futures position size?
Define a dollar-risk budget, calculate the number of ticks between entry and stop, multiply those ticks by the contract’s tick value, and divide the budget by the resulting risk per contract. Round down to the nearest whole contract. The futures position size calculator above performs this arithmetic automatically.
What if the calculator returns zero contracts?
One contract already exceeds the selected risk budget at that stop distance. A smaller contract may offer finer sizing, but changing contract size or stop distance should be based on your trading plan rather than on forcing a non-zero result.
Does this futures position size calculator include margin?
No. Margin is a separate broker or clearing requirement. This tool sizes from planned loss to the stop. Always confirm that the resulting position also complies with current broker or prop-firm margin and contract limits.
Does the calculator guarantee my maximum loss?
No. Stops can experience slippage, gaps or execution problems. Fees and market conditions can make realized loss larger than the estimate. The optional slippage and fee inputs are planning adjustments, not guarantees.
Can I use the futures position size calculator for ES and MES?
Yes. The preset list includes ES and MES with different tick values. It also includes NQ, MNQ, YM, MYM, RTY, M2K, CL, MCL, GC and MGC, plus a Custom option.
Can I use a fixed dollar risk instead of a percentage?
Yes. Enter a value in the fixed risk-budget field. When a positive fixed amount is present, the calculator uses it instead of the percentage-based budget.
Is 1% risk per trade the correct amount?
There is no universally correct percentage. Risk tolerance, strategy behavior, drawdown, account structure and financial circumstances differ. The percentage field is an input chosen by the user, not a recommendation from TradeboticsAI.
Can prop-firm traders use this tool?
Yes for arithmetic, but the trader must separately check the firm’s current rules. The calculator does not know your daily loss limit, trailing drawdown, consistency requirement, scaling plan or maximum contract rule.
Final Verdict: Futures Position Size Calculator for 2026
A good futures position size calculator should answer a narrow question clearly: given a defined risk budget and stop distance, how many whole contracts fit inside that budget? The answer depends on the exact contract’s tick size and tick value—not simply on account size or available margin.
Use the calculator before the order is sent, verify the contract specification, include realistic costs when useful, and treat zero contracts as a valid result. For active futures traders, this simple discipline can make position sizing more consistent across ES, MES, NQ, MNQ, crude oil, gold and other contracts.
This futures position size calculator remains an educational planning tool. It cannot choose a strategy, determine a suitable stop, predict slippage or guarantee the amount ultimately lost on a live trade.